REPORT
The State of AI Readiness in Consumer Goods
The Operating Model Decisions That Support Repeatable AI Deployment across Consumer Goods
How AI Moves from the Brand Team to the Shelf
Most consumer goods organisations are investing in AI, but few have turned pilots into repeatable results. This report examines what stands in the way and what the leaders do differently.
Foreword
Consumer packaged goods (CPG) organisations are exploring and deploying artificial intelligence (AI) across a growing range of brands, consumers, shoppers, commerce, customer and operational workflows. The research examines whether ownership, governance, measurement and ways of working that support this activity are evolving at the same pace. For CPG leaders, the question is not simply where AI can be applied. It is whether the organisation can evaluate, deploy and learn from use cases in ways that are repeatable, responsible and relevant to its commercial relationships.
As AI activity expands, teams may move at different speeds. Brand and portfolio leaders, ecommerce and digital media teams, shopper and retail-media teams, customer and sales organisations, product and supply-chain functions and data and technology teams can work with different systems, data, decision rights and planning cycles. Those differences can limit visibility and coordination, particularly where a use case depends on collaboration with media publishers, retail partners, distributors, marketplaces or other external parties.
Many processes connecting business, data, technology, legal, privacy, governance and risk teams were designed for longer planning cycles and more sequential handoffs. AI initiatives can require clearer decision rights, appropriate data access and consent practices, shared measures and sustained human oversight. Without these foundations, individual deployments may remain isolated and become more difficult to extend across teams, channels and use cases.
This report examines five operating model behaviours that are more common among the global cross-industry Leader cohort in the study. It offers consumer goods executives a practical framework for assessing their own readiness and identifying the decisions that can support more coordinated AI deployment.
Rashi Kacker
Global Industry Strategy Principal, Consumer Goods, Adobe
About the Research
This report draws on global research conducted by Incisiv on behalf of Adobe.
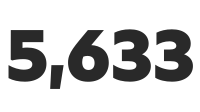
executives participated across 12 industries and 11 global markets.
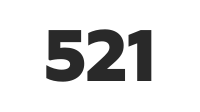
respondents represented consumer packaged goods.
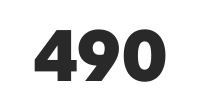
active CPG respondents were included in the analysis across the exploring, piloting, deploying, expanding and transforming stages of AI adoption.
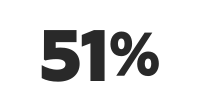
held positions at the vice president level or above.
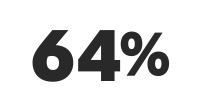
worked for organisations with more than US$1 billion in annual revenue.
MARKETS COVERED
Australia and New Zealand, Central Europe, India, Japan, Latin America, the Middle East, North America, Southeast Asia, South Korea, the United Kingdom and Ireland and Western Europe.
How Leaders Were Identified and Scored
The 342 AI Leaders referenced in this report come from the full study population of 5,633 senior executives across 12 industries. This is a global cross-industry cohort, not a CPG-specific group. It provides a benchmark for comparing the reported CPG findings with behaviours that are more common among Leaders.
How maturity was measured.
Each organisation was assessed across six operating model pillars, with every pillar scored on a scale of 1 to 5. The six scores were combined into an operating model maturity (OMM) composite.
Strategy
Clear AI vision with ownership and investment commitments.
Structure
Dedicated AI ownership with budget authority.
People
Roles and culture evolving for an AI-enabled environment.
Governance
Risk framework calibrated for AI velocity.
Technology
Infrastructure built for scale, not just pilots.
Workflows
AI embedded into how work is actually done.
How Leaders were identified.
To qualify as a Leader, an organisation had to meet two criteria: achieve an OMM Composite above 3.27 and operate at the expanding or transforming stage of AI deployment. Applying both criteria identified 342 Leaders across the 12 industries, equivalent to 6% of the 5,323 active respondents.
The designation reflects measured operating model maturity and deployment stage. It does not identify a CPG Leader cohort, establish that a behaviour caused scale or imply that the practices described in this report will produce the same result for every CPG organisation.
Executive Summary
Consumer packaged goods respondents report AI activity across a range of functions and workflows. The findings indicate that deployment does not automatically create the ownership, measurement and cross-functional coordination needed for repeatable execution. This report examines those operating model gaps and the behaviours that are more common among the global cross-industry Leader cohort.
The Industry Picture
61% of CPG respondents are in the Frozen Middle.
They have moved beyond early experimentation, but AI activity remains concentrated in the piloting and deploying stages. Individual functions may have deployed use cases, while the coordination needed for repeatable execution across teams remains limited. In CPG, that coordination can involve marketing, technology, legal, privacy, security, governance and commercial stakeholders. Where these groups operate with different priorities, systems, data permissions or planning cycles — evaluating and expanding a use case may become more difficult.
16% of CPG respondents have appointed a formal AI owner with a defined title and budget authority.
Elsewhere, accountability may be shared across functions, organised through committees, assigned project by project or remain unclear. Without explicit decision rights, organisations may find it harder to prioritise use cases, allocate resources, establish appropriate governance and resolve cross-functional questions as work progresses.
76% of CPG respondents manage the relationship between business and information technology (IT) through siloed, transactional or consultative ways of working.
These models can rely on requests, reviews and sequential handoffs. AI work may require closer coordination, shared objectives and key results (OKRs), suitable data and technology foundations and continued involvement from relevant privacy, legal, governance, security and risk stakeholders.
What Leaders Do Differently
Unless otherwise stated, “Leaders” refers to the global cross-industry cohort of 342 respondents whose organisations met both Leader criteria — an operating model maturity composite above 3.27 and operation at the expanding or transforming stage. They represent 6% of the 5,323 active respondents and are not a CPG-specific cohort.
Leaders are 5.8 times more likely to have a formal AI owner with title and budget authority.
Day-one measurement.
Leaders are more likely to define return on investment (ROI) before deployment. Among Leaders, 44% measure ROI comprehensively, compared with 12% of CPG respondents.
Genuine partnership.
Leaders are more likely to work through collaborative or integrated business-IT relationships. 81% operate at these levels, compared with 24% of CPG respondents.
Learning culture.
Leaders are less than 1% likely to report destructive failure patterns, compared with 28% of CPG respondents.
Empowered champions.
42% of Leaders identify finding and empowering internal champions as their most impactful culture action, ahead of every other lever measured.
PART ONE
The Industry Picture
Finding 01 — Most CPG Respondents Are in the Frozen Middle
61% of CPG respondents are in the Frozen Middle: AI is active in individual functions, while the coordination needed for repeatable execution across teams remains limited.
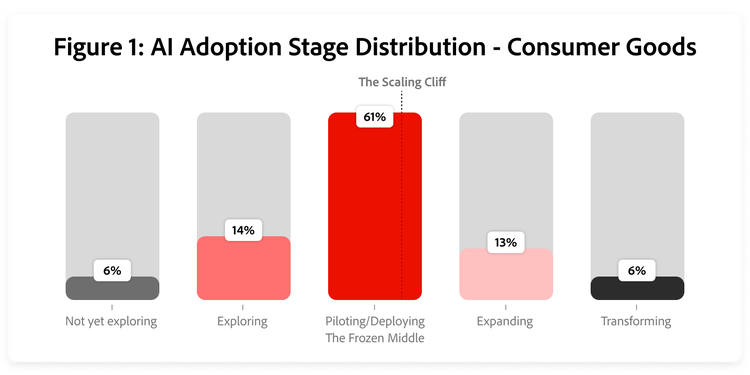
Share of Consumer Goods respondents at each adoption stage.
CPG respondents report AI deployment across individual functions, but many have not yet established the coordination needed to extend use cases more broadly. A content, consumer insight, commerce, shopper, customer, category or operational workflow may advance within one team while other relevant teams work with different systems, decision rights, data practices or priorities. This can create useful activity in individual areas without a consistent way to compare, govern or extend it.
The Frozen Middle describes CPG respondents at the piloting or deploying stages. The research reports that 61% are in this group. The designation does not show that progress has stopped or identify how long respondents have remained at a stage. It indicates that AI is active in pockets while the operating model practices needed for repeatable execution across teams remain limited.
Moving beyond the Frozen Middle may require clearer ownership, agreed decision rights, clearly outlined roles and responsibilities, appropriate data access and governance practices, rigorous legal review and shared measures across the functions involved in a use case.
The relevant mix will vary by organisation, business model, channel and relationship with distributors and/or other commercial partners. The next finding examines one foundational condition for this coordination: formal accountability with the authority to act.
Finding 02 — Only One in Six CPG Respondents Has Named a Formal AI Owner
Formal ownership is uncommon in the CPG respondent base, which can make it harder to resolve priorities, allocate resources and coordinate AI work across functions.
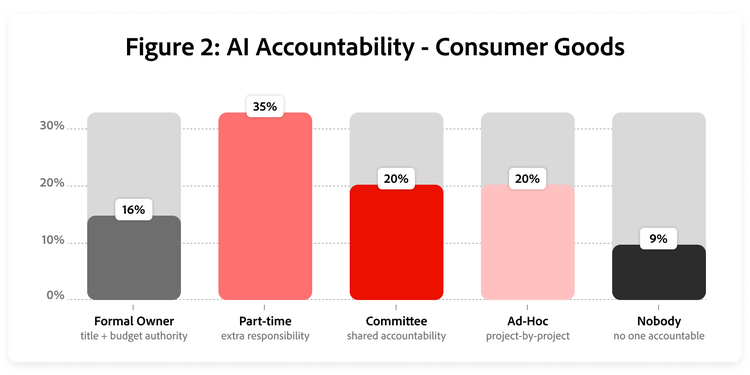
Distribution of AI ownership models in Consumer Goods.
AI accountability can involve brand and portfolio, commerce, consumer and shopper experience, customer and sales, product, operations, data, technology, legal, privacy, governance, security and risk teams. When responsibility is distributed across these groups without clear decision rights, it can be harder to resolve priorities, allocate resources or determine who is accountable for moving a use case through review and deployment.
The research reports that 16% of CPG respondents have a formal AI owner with a defined title and budget authority. This finding does not establish the appropriate role, reporting line or scope for every organisation. It does indicate that formal ownership is uncommon in the respondent base. Where an initiative crosses functions or depends on external commercial relationships, a role limited to one team may not have the authority needed to coordinate the full work.
Part-time ownership and committee-led accountability can be useful mechanisms for input and oversight, but they may leave binding decisions unresolved when no individual has a defined mandate. A formal owner can provide a clear point of accountability when the appointment includes the authority, resources and governance responsibilities relevant to the use cases in scope. The next finding examines another challenge in moving from proposed use cases to production: the evaluation path itself.
Finding 03 — Only 15 of Every 100 CPG AI Use Case Requests Reach Production
The largest absolute reduction occurs at the first transition, while the highest stage-to-stage attrition rate occurs later in the funnel.
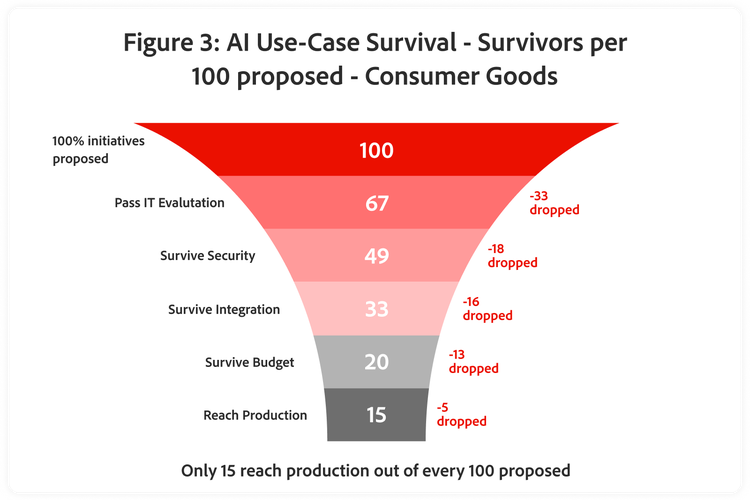
Mean survivors per 100 proposed AI initiatives in Consumer Goods, Global average: 15 per 100.
CPG AI use cases can span brand content, consumer and shopper engagement, communications, ecommerce, retail media, service, product, technology, productivity, commercial and supply chain workflows. A proposal can depend on several systems, data sources, approvals and teams. Production readiness therefore depends on aligning decision rights, data practices, safeguards and intended measures.
The chart shows that many proposed use cases are removed before production. Its first transition contains the largest absolute reduction, while a later transition has the highest proportional attrition rate. Together, these patterns suggest that early feasibility questions and later-stage dependencies can restrict progress. They do not show why any request was removed or whether any one function caused attrition, though suspected business impact and resource allocation within critical timelines may be leading factors in how teams prioritise.
The implication is not to bypass review. It is to clarify the intended outcome, the required data and permissions, system ownership, the relevant privacy, security, legal and governance considerations, the measurement approach during ideation and the business impact evaluation. This can give relevant teams a clearer basis to assess whether a proposed workflow is feasible and appropriate. The next finding considers how business-IT relationship models can shape this work.
Finding 04 — Most CPG Respondents Still Manage Business and IT through Handoffs
76% manage the relationship through siloed, transactional or consultative models, which can limit shared decision-making as AI work progresses.
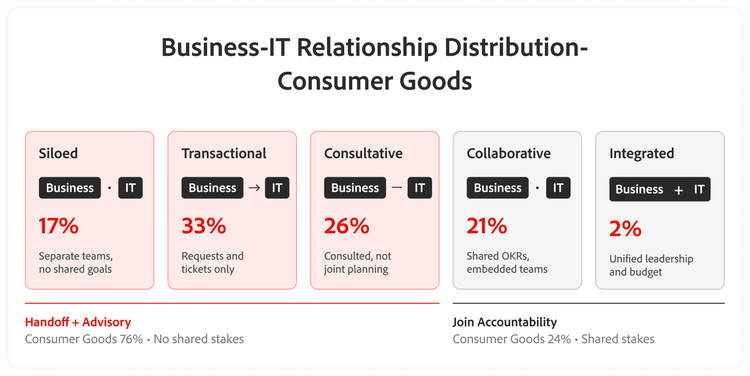
Distribution of Business-IT operating relationships in Consumer Goods.
AI work in CPG can connect brand, commerce, consumer and shopper experience, customer and sales, data and technology teams. It will also require privacy, legal, security, governance and risk input. Sequential requests and handoffs can make it harder to resolve data, integration, timing and measurement questions as a use case develops.
The research reports that 76% of CPG respondents manage business and IT through siloed, transactional or consultative relationship models — working on a project-by-project basis rather than through a product-centric model. These models can support necessary review and delivery activities, but may limit joint decision-making when a workflow requires iteration across teams. The finding does not show that every organisation needs the same structure or that relationship mode alone determines deployment outcomes.
Collaborative and integrated models are more common among the global Leader cohort. Shared objectives and key results (OKRs) can give business and technology teams a common basis for defining work, assessing safeguards and tracking progress. In CPG, participants should reflect the use case and the organisation’s commercial relationships. The next finding examines whether measurement is established early enough to evaluate AI initiatives.
Finding 05 — Comprehensive AI Measurement Remains Rare among CPG Respondents
12% of CPG respondents measure return on investment (ROI) comprehensively.
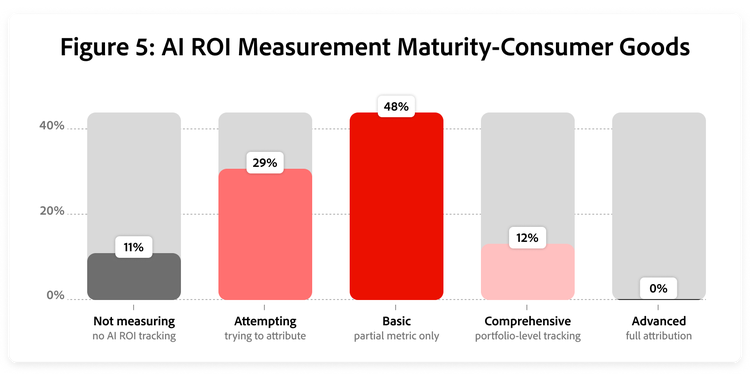
ROI Maturity distribution in Consumer Goods.
As AI becomes part of everyday work, CPG teams may track activity measures such as content produced, audiences created, workflows completed or time saved. These measures can show usage or efficiency. They do not, on their own, establish an effect on consumer, shopper, customer, commercial or operational outcomes.
The research reports that 12% of CPG respondents measure ROI comprehensively. Stronger evaluation begins before deployment: teams identify the intended outcome, establish an appropriate baseline and agree how results will be assessed. Once a workflow is in market, changing demand, pricing, promotion, media activity, distribution and other conditions can make its contribution more difficult to separate.
Pre-deployment measurement can give CPG leaders a clearer basis for evaluating whether to continue, adjust or extend an AI initiative. Relevant measures should reflect the use case, the available data and the organisation’s role in the customer or retail relationship. They should not be presented as guaranteed outcomes. Part two examines the operating model behaviours that are more common among the global Leader cohort.
PART TWO
What Leaders Do Differently
Leader Behaviour 01 — AI Scales More Effectively when a Named Leader Is Accountable for It
Leader vs Industry
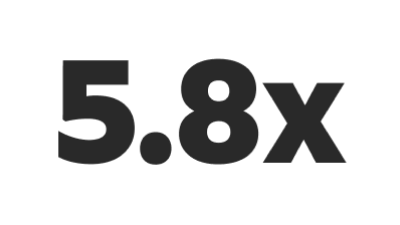
Leaders are 5.8x more likely to have a formal AI owner with title and budget authority. In Consumer Goods, 16% of organisations have named one. Leaders also operate Business-IT collaboratively 3.4x more often and measure ROI comprehensively 3.7x more often.
AI work in CPG can involve brand, commerce, consumer and shopper experience, customer and sales, product, operations, data and technology teams. It may also require privacy, legal, security, governance and risk input. When decisions span these boundaries, part-time owners, committees and ad hoc leads may lack authority to resolve priorities.
Leaders are 5.8 times more likely to have a formal AI owner with title and budget authority. This is an association, not evidence that formal ownership alone caused an organisation to scale AI. It indicates that a named leader is more common in the global Leader cohort. Formal ownership can provide a clear point of accountability for coordinating relevant decisions within an organisation’s governance and commercial relationships.
The role does not require a standard title or reporting line. Its scope should reflect the use cases it oversees and include authority beyond a single function. A chief marketing officer or another senior leader may fill the role. What matters is that the appointment carries explicit mandate, appropriate resources, defined decision rights and active engagement with the teams a use case depends on, including legal, security and technology. The next behaviour examines measurement before deployment.
Leader Behaviour 02 — Leaders Define How Success Will Be Assessed before an AI Use Case Launches
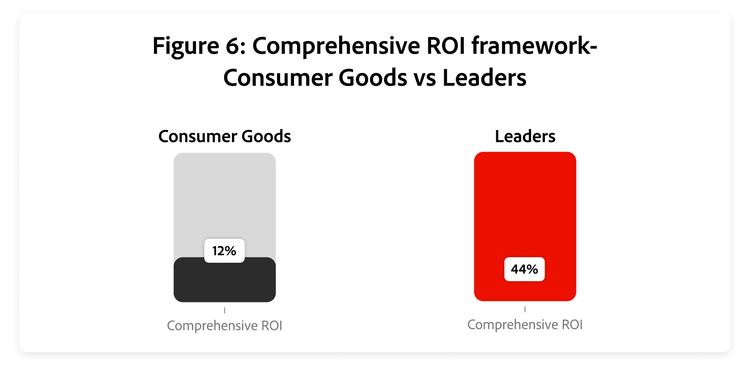
Share with Comprehensive or Advanced ROI framework. Leaders cohort: 342 organisations across all 12 industries.
Measurement is most useful when it is designed with the use case rather than added after deployment. CPG teams may need to consider outcomes relevant to brand, consumer and shopper experience, commerce, customer relationships, product or operations. The appropriate measure depends on the use case, available data, organisational role and relationship with any external partner.
The research reports that 44% of Leaders measure ROI comprehensively, compared with 12% of CPG respondents. This is an association, not evidence that comprehensive measurement caused AI scale. It indicates that a developed measurement practice is more common among the global Leader cohort. Leaders may define the intended outcome, baseline and assessment approach before a workflow begins.
Early planning does not guarantee a result or eliminate attribution challenges. Conditions can change after launch, making it harder to separate an AI workflow’s contribution from other activity. Defining the measures, data sources, responsibilities and review timing in advance can give teams a clearer basis to interpret results and decide whether to adjust, continue or extend a use case. The next behaviour examines how partnership supports this work.
Leader Behaviour 03 — Business and IT Share Accountability for the Work and Its Assessment
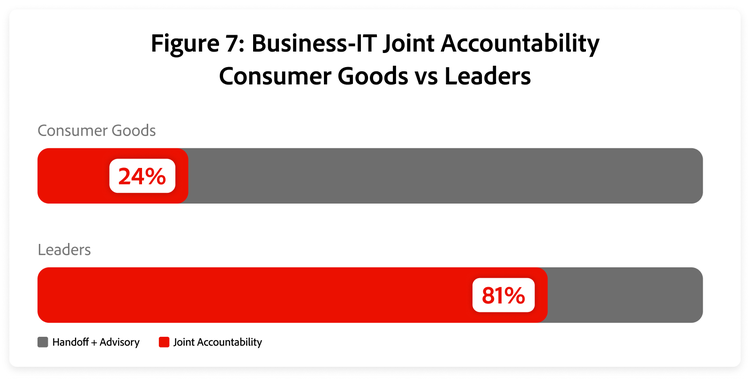
Joint accountability = Collaborative + Integrated. Handsoff + Advisory = Siloed + Transactional + Consultative.
AI work in CPG may require business and IT to coordinate around data, technology, delivery, measurement and safeguards. A sequential handoff can create friction when questions about data access, integration, timing or governance arise. Consultative relationships can provide useful advice, but they do not necessarily create shared accountability for the outcome.
The research reports that 81% of Leaders operate at the collaborative or integrated level, compared with 24% of CPG respondents. This is an association, not evidence that a relationship model alone caused scale. It indicates that closer business-IT relationships are more common among the global Leader cohort. In these models, relevant teams can contribute when work is defined, rather than receiving a completed request for review or delivery.
Shared accountability can continue through measurement and ongoing review. Shared objectives and key results (OKRs) can give business and IT a common basis for defining work, resolving issues and assessing progress. Participants, decision rights and safeguards should reflect the use case and the organisation’s commercial relationships. The next behaviour examines how learning practices can support AI work over time.
Leader Behaviour 04 — Leaders Turn Underperformance into Shared Learning
AI work can underperform because of data, workflow, evaluation, adoption or changing conditions. In CPG, a lesson may matter to brand, commerce, consumer and shopper experience, customer and sales, product, operations, data or technology teams. If it stays within one team, others may repeat the same assumption in later work.
The research reports that 28% of CPG respondents report destructive failure patterns, compared with under 1% of Leaders. This is an association, not evidence that failure response alone caused scale. It indicates that constructive learning practices are more common among the global Leader cohort. The finding should not be interpreted as a reason to lower responsible review standards or accept avoidable harm.
A learning culture can be visible in regular operating reviews. Teams can examine what underperformed, which assumptions were unsupported, what safeguards or decisions need adjustment and what should change before the next use case. Senior leaders can make time for reflection and ensure relevant learning is shared with teams facing comparable decisions. The next behaviour examines the role of empowered champions.
Leader Behaviour 05 — Leaders Support Practitioners Who Can Share Responsible AI Practices with Their Peers
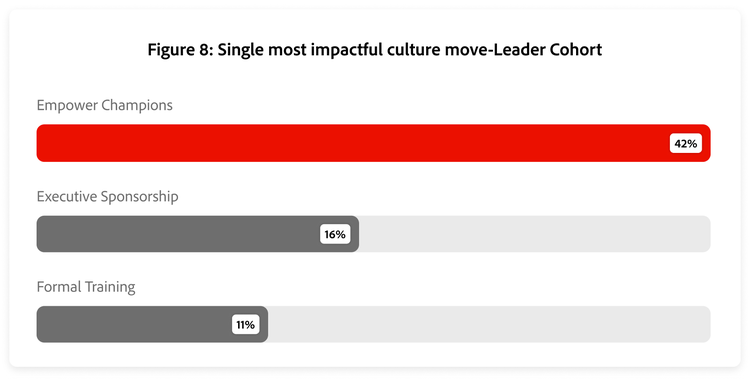
Leader* top-cited culture lever, n=342 Leaders across all 12 industries.
Adoption can be easier when people see a colleague use AI in familiar work. In CPG, that may involve brand content, consumer or shopper engagement, ecommerce, retail media, customer service, product, commercial or operational workflows. These examples illustrate possible contexts; they do not establish a measured outcome or imply that every organisation uses AI in the same way.
The research reports that 42% of Leaders identify finding and empowering internal champions as their most impactful culture action, ahead of every other lever measured. This is an association, not evidence that champions alone caused scale. It indicates that this practice is more common among the global Leader cohort. Champions can help peers understand a workflow, surface questions and share learning within appropriate governance boundaries.
Support can include recognition, time, resources and responsibilities to share an approach with an adjacent team. It should not bypass decision rights, privacy, security, legal or other review requirements. Organisations can pair practitioner-led learning with guidance, evaluation methods and governance support. Together, these five behaviours offer a framework for assessing CPG AI readiness.
5 Moves that Build the Operating Model in CPG
These actions translate the five Leader behaviours into practical next steps for CPG executives. They can be adapted to the organisation’s business model, use cases and commercial relationships.
- Name an AI owner with cross-functional decision rights.
Assign a named senior leader with explicit mandate, resources and decision rights for the AI use cases in scope. Relevant participants may include brand, commerce, consumer and shopper experience, customer and sales, product, operations, data, technology and risk functions. The purpose is to create a clear point of accountability when decisions cross teams, not to replace existing governance or reporting lines - Define the outcome and assessment approach before deployment.
Before approving a use case, define its intended outcome, the baseline, relevant data and permissions, assessment method and review timing. Involve the functions responsible for implementation, measurement and safeguards early. This gives teams a clearer basis to determine whether a workflow is feasible, appropriate and worth extending. - Make business and IT jointly accountable for cross-functional use cases.
Establish shared objectives and key results for use cases that require business and IT coordination. Agree on the relevant roles, data practices, integration requirements, safeguards and escalation path at the start of the work. Shared accountability can help teams address issues as they arise, while preserving appropriate privacy, security, legal, governance and risk review. - Turn underperformance into shared learning.
Build regular reflection into operating reviews. Examine what underperformed, which assumptions were unsupported, what needs to change and what learning should be shared. This should include responsible review of any material impact on consumers, shoppers, customers, employees or commercial partners. - Support practitioners who can share responsible AI practices.
Identify practitioners using AI in relevant workflows and give them structured opportunities to share what they have learnt. Provide recognition, time, guidance and appropriate support to help peers evaluate and adapt practices. Practitioner-led learning should operate within established decision rights and review requirements.
CONCLUSION
AI Readiness in CPG Depends on the Operating Model Around the Work
CPG respondents report AI activity across individual functions, while the findings point to operating model gaps in ownership, measurement, business-IT partnership, learning and practitioner support. The global cross-industry Leader cohort provides a benchmark for behaviours that are more common among organisations with higher measured operating model maturity and later-stage deployment. It does not define a CPG Leader group or establish that any individual behaviour caused scale.
For CPG executives, readiness is not only a question of selecting tools or use cases. It is also a question of decision rights, suitable data practices, assessment, collaboration and responsible oversight. These practices should reflect the organisation’s business model, the use case and the roles of consumers, shoppers, customers, employees, retailers, distributors, marketplaces and other commercial partners. Privacy, consent, security, legal, governance and human-oversight considerations should remain visible throughout the work.
A practical next step is to select a priority AI use case and assess whether its ownership, intended outcome, data and permissions, safeguards, measurement approach and cross-functional responsibilities are clear before deployment. This can give relevant leaders a focused basis for identifying what needs to change and where to begin.
About Adobe
About Incisiv
Recommended for you