Report
The State of AI Readiness in Industrial Manufacturing
The operating model decisions that help scale AI across demand generation, channel, and aftermarket.
Turning AI Momentum into Repeatable Scale
For The State of AI Readiness in Industrial Manufacturing study, we surveyed executives to understand how industrial manufacturers are adopting AI across marketing and customer experience workflows, where progress is getting stuck, and what operating-model practices can help organizations move from individual deployments to repeatable scale.
Foreword
Industrial manufacturing no longer needs to ask whether AI belongs in the commercial engine. Respondents report activity at every stage from exploration to transformation, while use cases are emerging across customer engagement, demand planning, service, and operations. The harder question is how to move from individual deployments to repeatable scale.
This challenge extends beyond technology. AI must advance with the people, processes, data, and governance needed to support it. Industrial manufacturers also coordinate across global markets, complex distributor and channel structures, and rising customer expectations. This baseline complexity is distinct from the caution created by AI itself.
That caution can be rational. AI can touch engineering-heavy, documentation-sensitive, safety- and compliance-bound workflows, where errors may create regulatory, reputational, or operational exposure. Progress, therefore, depends on clear ownership across demand generation, channel, and aftermarket; genuine partnership between business and IT; and measurement established before deployment. Fragmented technology estates can make that coordination harder.
The research shows where operating model gaps are concentrated and identifies behaviors more common among the global cross-industry Leaders. Read this report as a benchmark, not a forecast. Its purpose is to help executives assess what the operating model can support and decide what to build next.
Director, Global Industry Strategy, Industrial Manufacturing
Adobe
About the Research
This report draws on global research conducted by Incisiv on behalf of Adobe.
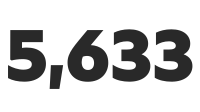
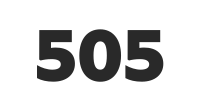
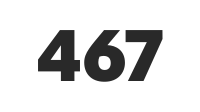
respondents formed the active industrial manufacturing respondent base. They reported a current state of AI adoption in marketing and customer experience workflows across five stages: exploring, piloting, deploying, expanding, and transforming.
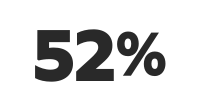
of respondents held positions at the vice president level or above, within the industrial manufacturing cohort.
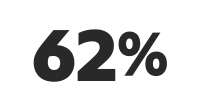
MARKETS COVERED
Markets covered were Australia and New Zealand, Central Europe, India, Japan, Latin America, the Middle East, North America, Southeast Asia, South Korea, the United Kingdom and Ireland, and Western Europe.
How Leaders Were Identified and Scored
How Maturity Was Measured
Each organization was assessed across six operating model pillars and scored on a scale of 1 to 5. The six scores were combined into an operating model maturity (OMM) composite.

Strategy
Clear AI vision with ownership and
investment commitments.

Structure
Dedicated AI ownership with budget authority.

People
Roles and culture evolving for
an AI-enabled environment.

Governance
Risk frameworks calibrated for AI velocity.

Technology
Infrastructure built for scale, not just pilots.

Workflows
AI embedded into how work is actually done.
How Leaders Were Identified
To qualify as a Leader, an organization had to meet two criteria: achieve an OMM composite above the top-quartile threshold of 3.27 and operate at the expanding or transforming stage of AI deployment. Unless otherwise stated, “Leaders” refers to the global cross-industry cohort of 342 respondents whose organizations met the Leader criteria, representing 6% of the 5,323 active respondents.
These organizations have established the ownership, governance, measurement, and ways of working needed to make AI deployment repeatable and sustainable. The Leader designation is based on measured operating-model maturity and deployment stage, providing a consistent view of how more mature AI operators organize and run their programs.
Executive Summary
The Industry Picture
Of the industrial manufacturing respondents,
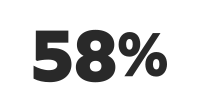
are at the piloting or deploying stage, forming the frozen middle.
AI is active within individual functions, but scaling across demand generation, channel engagement, aftermarket service, and supporting systems remains difficult. This concentration should not be read simply as a lack of ambition or readiness. Documentation-sensitive, safety- and compliance-bound workflows create legitimate caution, while global operations and multi-tier channel structures add coordination complexity.
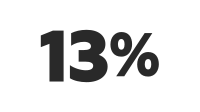
have a formal AI owner with a defined title and budget authority.
Elsewhere, accountability is part-time, committee-led, assigned on a project-by-project basis, or absent. When an initiative requires customer data, distributor participation, technical content, and compliance review, no individual function may have the authority to resolve competing priorities or make a binding decision.
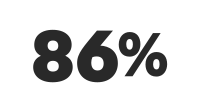
operate in siloed, transactional, or consultative business-IT relationship modes.
Sequential handoffs are compounded by fragmented technology estates built through years of independently procured solutions and, in some organizations, merger and acquisition activity. Shared objectives and key results (OKRs) can improve coordination, but they cannot replace the architectural work required to connect customer, channel, service, and operational data.
What Leaders Do Differently
The 342 Leaders identified across the broader cross-industry sample show five operating-model behaviors that are relevant to industrial manufacturing:

Leaders are 7.2 times more likely to have a formal AI owner with the title, mandate, and budget authority to work across functions.

44% of Leaders measure return on investment (ROI) comprehensively, compared with 7% of the active industrial manufacturing respondent base.

81% of Leaders operate at the Collaborative or Integrated level, compared with 14% of the active industrial manufacturing respondent base.

44% of the active industrial manufacturing respondent base reports blame or repeated failure when AI initiatives underperform. Among Leaders, the figure is under 1%.

42% of Leaders identify finding and empowering internal champions as the people or culture action with the greatest impact on their ability to scale AI.
Part One
The Industry Picture
Finding 01: The Frozen Middle
Most industrial manufacturing respondents are in the piloting or deploying stages.
58% of respondents are in these two stages, forming a frozen middle in which AI is active but has not yet reached repeatable deployment across the operating model.
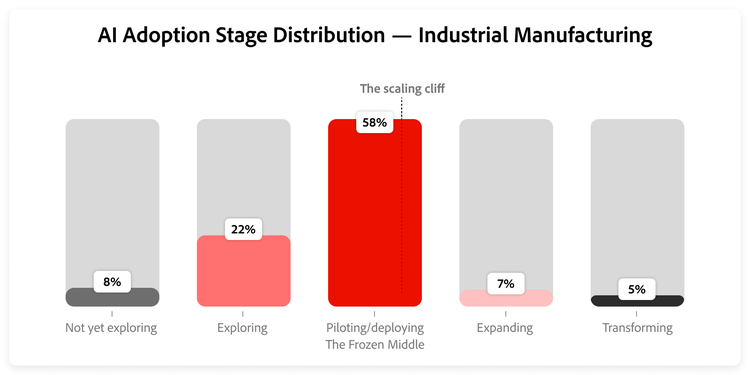
Share of Industrial Manufacturing respondents at each adoption stage.
Industrial manufacturing respondents are adopting AI, with activity concentrated midway through the journey. Across the cohort, 58% are in the piloting or deploying stages, forming the frozen middle. Account intelligence, distributor content, and aftermarket engagement can operate within individual functions without becoming repeatable across the commercial model.
Caution in this environment can be rational. Generative AI can touch engineering-heavy, documentation-sensitive, safety- and compliance-bound workflows, where errors may create regulatory exposure. In some markets with few dominant competitors and limited growth, a misstep that costs customer trust or market share can be difficult to recover. Global operations and multi-tier channels add coordination complexity.
This concentration reflects more than isolated deployment schedules. Scaling requires channel, service, data, risk, and technology teams to align across boundaries not designed for rapid iteration. Without authority across those seams, decisions about data rights, integration, and risk are deferred. Ownership becomes the issue to examine.
Finding 02: The Ownership Vacuum
Only 13% of active industrial manufacturing respondents report formal AI ownership.
Most of the active respondent base reports part-time, committee-led, ad hoc, or unassigned accountability rather than an owner with a formal title and budget authority.
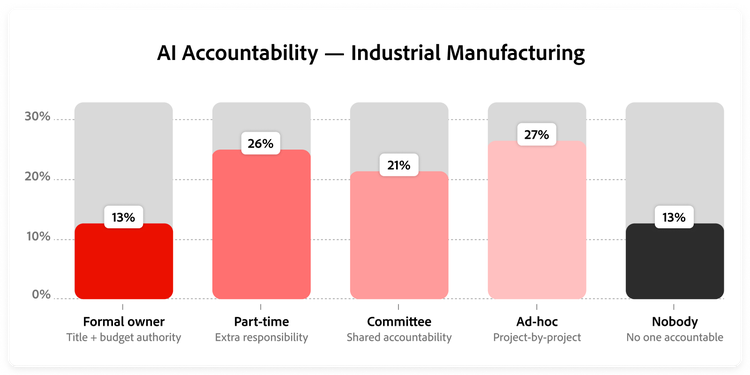
Distribution of AI ownership models in Industrial Manufacturing.
Among the 467 active industrial manufacturing respondents, 13% report that their organization has a dedicated AI owner with a formal title and budget authority. Others describe accountability as part-time, committee-led, ad hoc, or absent. Assigned responsibility does not necessarily include authority to set priorities, commit funding, or resolve conflicts across functions.
Commercial AI initiatives often cross demand generation, distributor management, aftermarket service, data, and technology. An account-based marketing program may need install-base telemetry, distributor customer relationship management access, and technical content inputs. When authority ends at each function’s boundary, decisions about data use, integration, and campaign priorities pass through several owners without one person being able to make a binding call.
The effect extends beyond approval. Fragmented accountability leaves use cases exposed during formal review because ownership of the data, systems, risk, and commercial outcome remains unsettled. This leads directly to the point of pressure: how proposed ideas move into production.
Finding 03: The Approval Barrier
For industrial manufacturing respondents, only 13 of every 100 AI use case requests reach production.
Among the active respondent base, the median reported production launch rate is 13 out of every 100 requests, following IT, security, integration, and budget review.
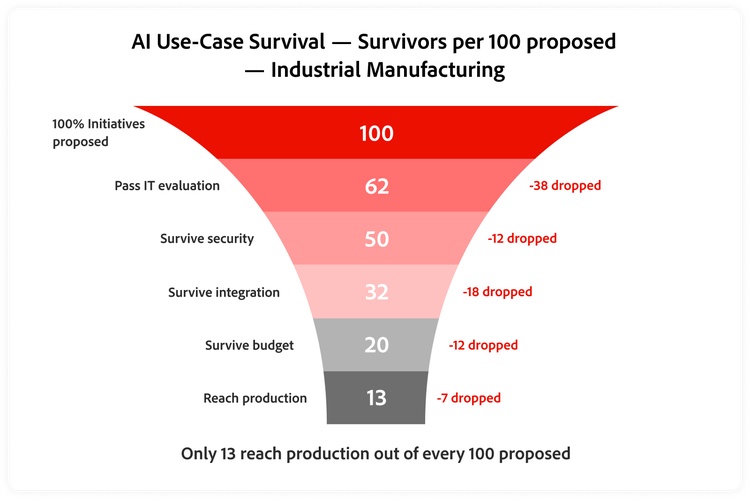
Mean survivors per 100 proposed AI initiatives in Industrial Manufacturing. Global average: 15 per 100.
Across the active industrial manufacturing respondent base, the use-case funnel narrows sharply: a median of 13 out of every 100 requests reaches production. The largest reduction occurs at the initial IT evaluation, followed by security, integration, and budget review. Each gate serves a legitimate purpose, but their cumulative effect shows how difficult it is for an idea to survive the full path.
Commercial value is one of several considerations. Reviews may focus on system compatibility, data access, security, compliance, and budget before customer or commercial value can be tested. A use case spanning customer relationship management systems, distributor portals, and manufacturing execution systems can be stopped by ownership or integration constraints even when its business case remains promising.
The funnel exposes unresolved accountability. When data rights and system ownership remain unsettled, ideas enter review with questions no function can resolve. The next finding examines how business and IT shape that process.
Finding 04: Business-IT Handoff
86% of active industrial manufacturing respondents report siloed, transactional, or consultative business-IT relationships.
Sequential handoffs reflect long technology and capital cycles and can be compounded by fragmented systems accumulated through independent technology purchasing.
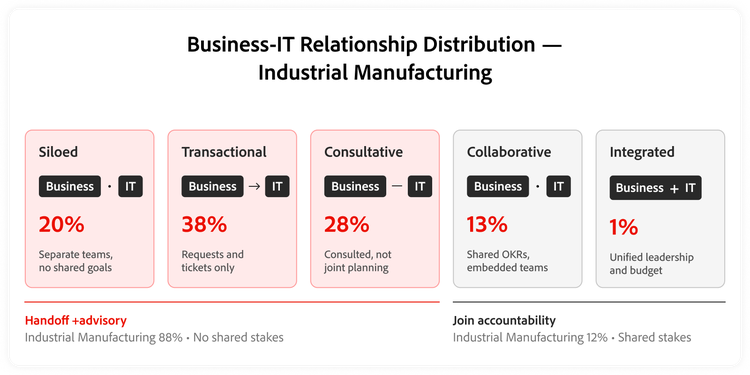
Distribution of Business-IT operating relationships in Industrial Manufacturing.
Among the active industrial manufacturing respondent base, 86% characterize the business-IT relationship as siloed, transactional, or consultative. In these modes, business teams may define the request before IT becomes involved, leaving IT with sole responsibility for delivery. That cadence can suit long enterprise resource planning, manufacturing execution system, and controls upgrade cycles, but AI-driven commercial workflows require faster iteration and shared accountability.
The handoff reflects more than a legacy operating design. Years of point solutions purchased independently, sometimes through merger and acquisition activity, can leave customer, distributor, service, and operational data spread across disconnected systems. This accumulated technical debt makes integration genuinely difficult and creates a practical ceiling on what the current infrastructure can support.
Shared objectives can improve alignment, but cannot resolve architectural fragmentation alone. The working relationship and underlying data environment jointly shape whether deployment becomes repeatable. Until both evolve, measurement remains fragmented, leading to the final finding.
Finding 05: The Measurement Gap
Only 7% of active industrial manufacturing respondents report comprehensive AI return on investment measurement.
Basic measures can provide useful evidence of adoption and delivery, but they do not establish whether AI changed a customer or commercial outcome.
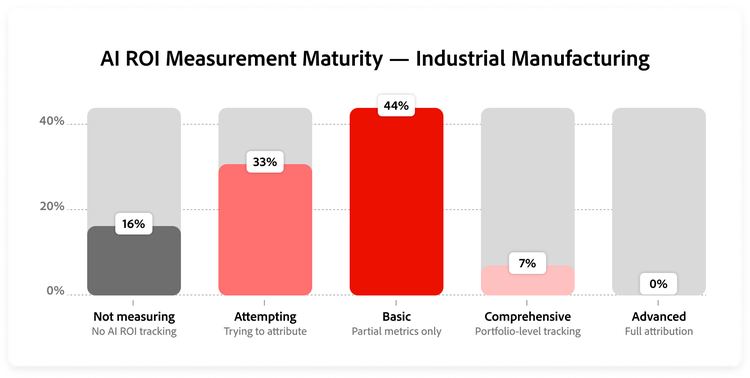
ROI maturity distribution in Industrial Manufacturing.
Among the active industrial manufacturing respondents, only 7% report a comprehensive return-on-investment framework. Most respondents report basic metrics, are attempting measurement but struggling, or are not measuring. This indicates that measurement is present in many programs, but often stops before establishing a customer or commercial outcome.
Basic measures can confirm that a tool was used, an audience was segmented, or a campaign ran. These are practical measurement choices, particularly when data is distributed across markets, channel partners, and service systems. However, they cannot show whether AI improved pipeline conversion, distributor sell-through, or service-contract renewal.
The measurement window narrows after deployment. Once an AI-driven program is live, its contribution can be difficult to separate from demand conditions, inventory positions, and service capacity. Without a pre-deployment baseline, executives have less evidence for deciding whether to extend or fund the program. This gap sets up the Leader behaviors examined next.
Part Two
What Leaders Do Differently
Leader Behavior 01: Real Ownership
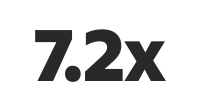
Leader vs Industry
Across the global cross-industry Leader cohort, formal AI ownership with title and budget authority is 7.2 times more common than among the active industrial manufacturing respondent base. Only 13% of that base reports this level of ownership. The comparison highlights the difference between assigning responsibility and giving someone authority to act across functions.
In industrial manufacturing, commercial AI initiatives can span demand generation, distributor management, aftermarket service, data, technology, and risk. A formal owner provides a point for resolving conflicts over priorities, funding, data access, and acceptable risk when no individual function controls the full workflow.
Formal ownership does not remove integration constraints, regulatory review, or deployment failure. It clarifies who is accountable for responding to them. That owner can keep the commercial outcome visible, establish measurement expectations, and carry lessons from one deployment into the next. For industrial manufacturing respondents, this is the foundation for the remaining Leader behaviors.
Leader Behavior 02: Day-One Measurement
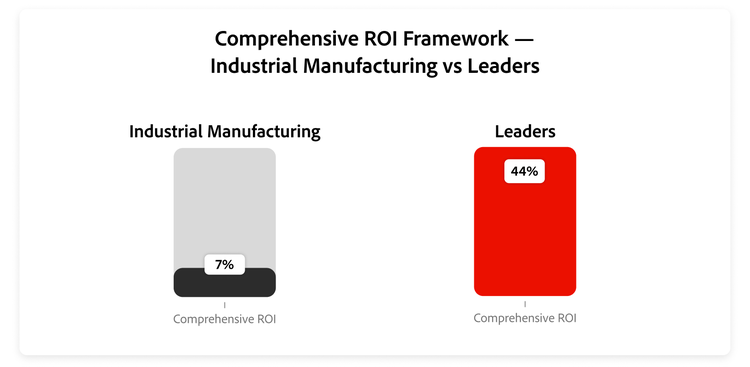
Share with Comprehensive or Advanced ROI framework. Leaders cohort: 342 organizations across all 12 industries.
Across the cross-industry Leader cohort, 44% report a comprehensive return on investment framework, compared with 7% of the active industrial manufacturing respondent base. The difference concerns more than reporting. Comprehensive measurement links deployment to a defined customer or commercial outcome and establishes how that outcome will be assessed.
For industrial manufacturing, this may mean setting baselines for pipeline conversion, distributor sell-through, service-contract renewal, or content performance before deployment. Agreement is also needed on attribution across markets, channel partners, and service cycles. The active respondent base has not yet built this discipline consistently, with most reporting basic measurement, difficulty measuring, or no measurement.
Day-one measurement does not remove long sales cycles or external factors that affect results. It gives teams an agreed baseline for interpreting them. That evidence can guide whether a program should be adjusted, extended, or stopped, while helping the organization carry learning from one deployment to the next.
Leader Behavior 03: Genuine Partnership
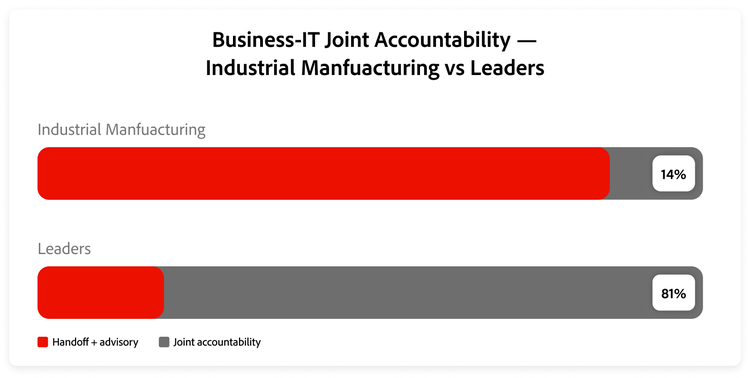
Joint accountability = Collaborative + Integrated. Handoff + Advisory = Siloed + Transactional + Consultative.
Across global cross-industry Leaders, 81% report collaborative or integrated business-IT relationships, compared with 14% of the active industrial manufacturing respondent base. In these modes, business and IT share accountability for outcomes rather than limiting their relationship to requests, advice, or delivery.
For industrial manufacturing, genuine partnership begins before a use case enters development. Commercial, data, technology, security, and compliance teams shape the brief together, agree on the customer or commercial objective, and identify integration constraints early. Most active respondents have not yet reached this relationship model, leaving shared decisions to be resolved later in the process.
Partnership does not consolidate fragmented architecture or remove regulatory risk. It changes how teams respond to those constraints. Shared objectives keep both sides engaged through scoping, deployment, and measurement, while joint accountability reduces the chance that unresolved issues are passed between functions. This gives industrial manufacturing initiatives a more stable basis for continuous iteration and learning.
Leader Behavior 04: Learning Culture
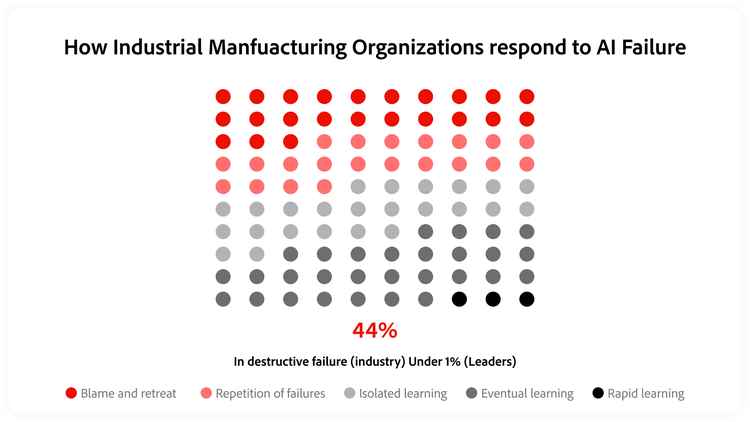
Each dot represents one of every 100 Industrial Manufacturing organizations. Destructive = Blame and retreat + Repetition of failures.
Among the active industrial manufacturing respondent base, 44% report that AI underperformance leads to blame and retreat or repetition of failure. Among the global cross-industry Leaders, the figure is under 1%. This difference does not suggest that Leaders avoid barriers or failed initiatives. They report a different response.
Industrial manufacturing programs often operate across long sales cycles, annual distributor plans, and equipment service schedules. When an account model or engagement workflow underperforms, teams may face pressure to continue without examining the cause. If learning remains within one function or market, another team can carry the same assumptions into its next deployment.
A learning culture makes underperformance available for structured review. Leaders are more likely to respond through rapid or eventual learning rather than blame or repetition. This approach does not lower the stakes involved. It helps teams identify what changed, preserve useful evidence, and adjust the next deployment.
Leader Behavior 05: Empowered Champion
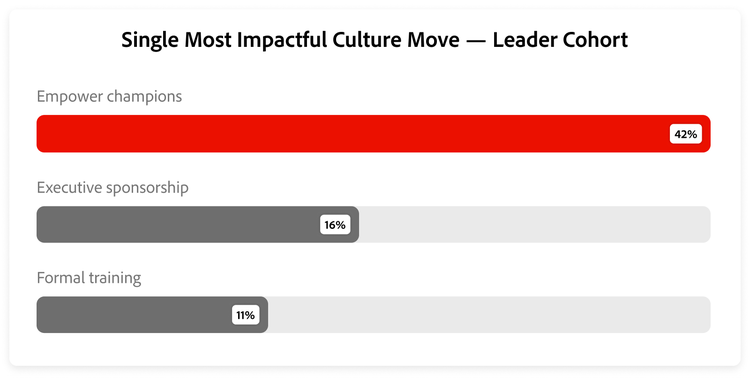
Leaders’ top-cited culture lever. n=342 Leaders across all 12 industries.
Among global cross-industry Leaders, 42% identify empowering internal champions as the people or culture change with the greatest impact on scaling AI. This exceeds executive sponsorship at 16% and formal training at 11%. The pattern points to the value of practitioners who can show how AI changes real work.
In industrial manufacturing, champions may emerge in demand generation, channel marketing, aftermarket service, or content operations. Their influence comes from demonstrating a result in a workflow, market, or partner environment. That practical evidence can make adoption more credible than a general message delivered from the center.
Champions do not replace formal ownership, shared governance, or technical support. They need permission, time, recognition, and cross-functional reach to extend learning beyond one team. Industrial manufacturing respondents report challenges moving from individual to shared practices. When champions are empowered, they can surface friction early, share evidence, and help teams respond to setbacks.
Five Moves That Build the Operating Model in Industrial Manufacturing
Each move reflects behavior more common among global cross-industry Leaders and builds on existing investments.
Appoint one executive, such as the chief marketing officer, Head of Commercial, or a senior customer experience leader, with a formal title, dedicated budget, and authority across demand generation, channel engagement, and aftermarket service. Technology, data, risk, and operations should participate in governance. The role creates a clear decision point when priorities, funding, or acceptable risk conflict.
Before approving the next deployment, require the initiative owner, marketing lead, finance partner, and data team to define the customer or commercial outcome, baseline, attribution method, and review window. Connect measures to pipeline conversion, distributor engagement, service-contract renewal, or another supported objective. This preserves evidence before market and operating conditions change.
Have commercial and technology leaders jointly map the systems, data rights, integration dependencies, and governance requirements for priority use cases. Set shared objectives and key results, then identify where fragmented platforms require consolidation or remediation. Include security, compliance, operations, and channel owners. This aligns delivery while addressing the technical debt that shared targets alone cannot remove.
Add a structured AI review to the commercial operating rhythm, owned by marketing or customer experience with technology, risk, and relevant channel or service teams. Examine underperformance without lowering safety or compliance standards. Record what changed, what failed, and what should be tested next, so lessons move beyond the originating function.
Identify practitioners who have demonstrated value in demand generation, channel marketing, aftermarket engagement, content operations, or another supported workflow. Give them recognition, time, a small budget, and permission to extend the practice to one adjacent team. Formal ownership and shared infrastructure should support them, so local credibility becomes a repeatable capability rather than an isolated success.
Conclusion
Turn AI Activity into Repeatable Scale
Most industrial manufacturing respondents report active AI adoption across marketing and customer experience workflows, but activity remains concentrated in piloting and deploying. Moving beyond that concentration requires more than additional tools. It requires an operating model that can coordinate decisions across commercial teams, channel partners, technology, data, risk, and compliance.
The cross-industry Leader benchmark points to a connected set of behaviors: formal ownership, measurement established before deployment, shared business-IT accountability, structured learning, and empowered practitioners. These behaviors do not remove integration constraints, regulatory exposure, or the complexity of global channel operations. They give organizations a clearer way to respond.
The practical next step is to apply this model to one priority commercial or customer experience use case. Name the accountable owner, define the outcome and baseline, and map the data, architecture, and governance dependencies before deployment. That discipline creates a stronger basis for deciding what to scale, what to change, and where further investment is justified.
About Adobe
Adobe empowers organizations to create impactful digital experiences. Our portfolio of customer-experience products and services helps businesses put every interaction in context, understand what each customer needs right now, and design and deliver digital experiences that build loyalty and drive growth. Visit adobe.com to know more.
About Incisiv
Incisiv is an industry insights and strategy firm combining close to a decade of industry trend data with primary research, messaging architecture, and content development to help enterprises navigate transformation, evaluate solutions, and unlock growth. Visit incisiv.com to know more.
Recommended for you